Family life is full of small financial choices, from the weekly food shop to paying for school trips, childcare, transport and home repairs. While big money decisions matter, everyday habits often reduce stress the most. By planning ahead, comparing options and keeping communication open, families can make their money work harder without feeling constantly restricted.
Transport is a good example of this kind of thing. Many households rely on a dependable car for work, school runs and appointments. For some families, leasing with poor credit may be a good option, but it is still important to check affordability, total costs and contract terms carefully. Looking beyond the monthly payment helps avoid surprises linked to mileage limits, deposits, servicing or early exit fees.
Here are some other everyday money decisions that can make family life much easier:
Build a Realistic Household Budget
A family budget should reflect real life, not an ideal version of it. Start by listing essential costs such as rent or mortgage payments, council tax, utilities, food, insurance, travel and childcare. Then add irregular expenses, including birthdays, uniforms, car maintenance, Christmas and emergency repairs.
It can help to divide your household spending into “must pay”, “useful” and “nice to have” categories. This makes it easier to see where your money is going and where you can make small adjustments.
Plan Meals and Food Shopping
Food is one of the easiest areas for family spending to drift. Planning meals for the week can reduce waste, cut down on last-minute takeaways and make shopping quicker. Before going to the supermarket, check your cupboards, freezer, and fridge so you don’t buy items you already have.
Using a shopping list and comparing own-brand products can make a noticeable difference over time. Batch cooking is also useful for busy families, especially on evenings filled with clubs, homework or late finishes at work.
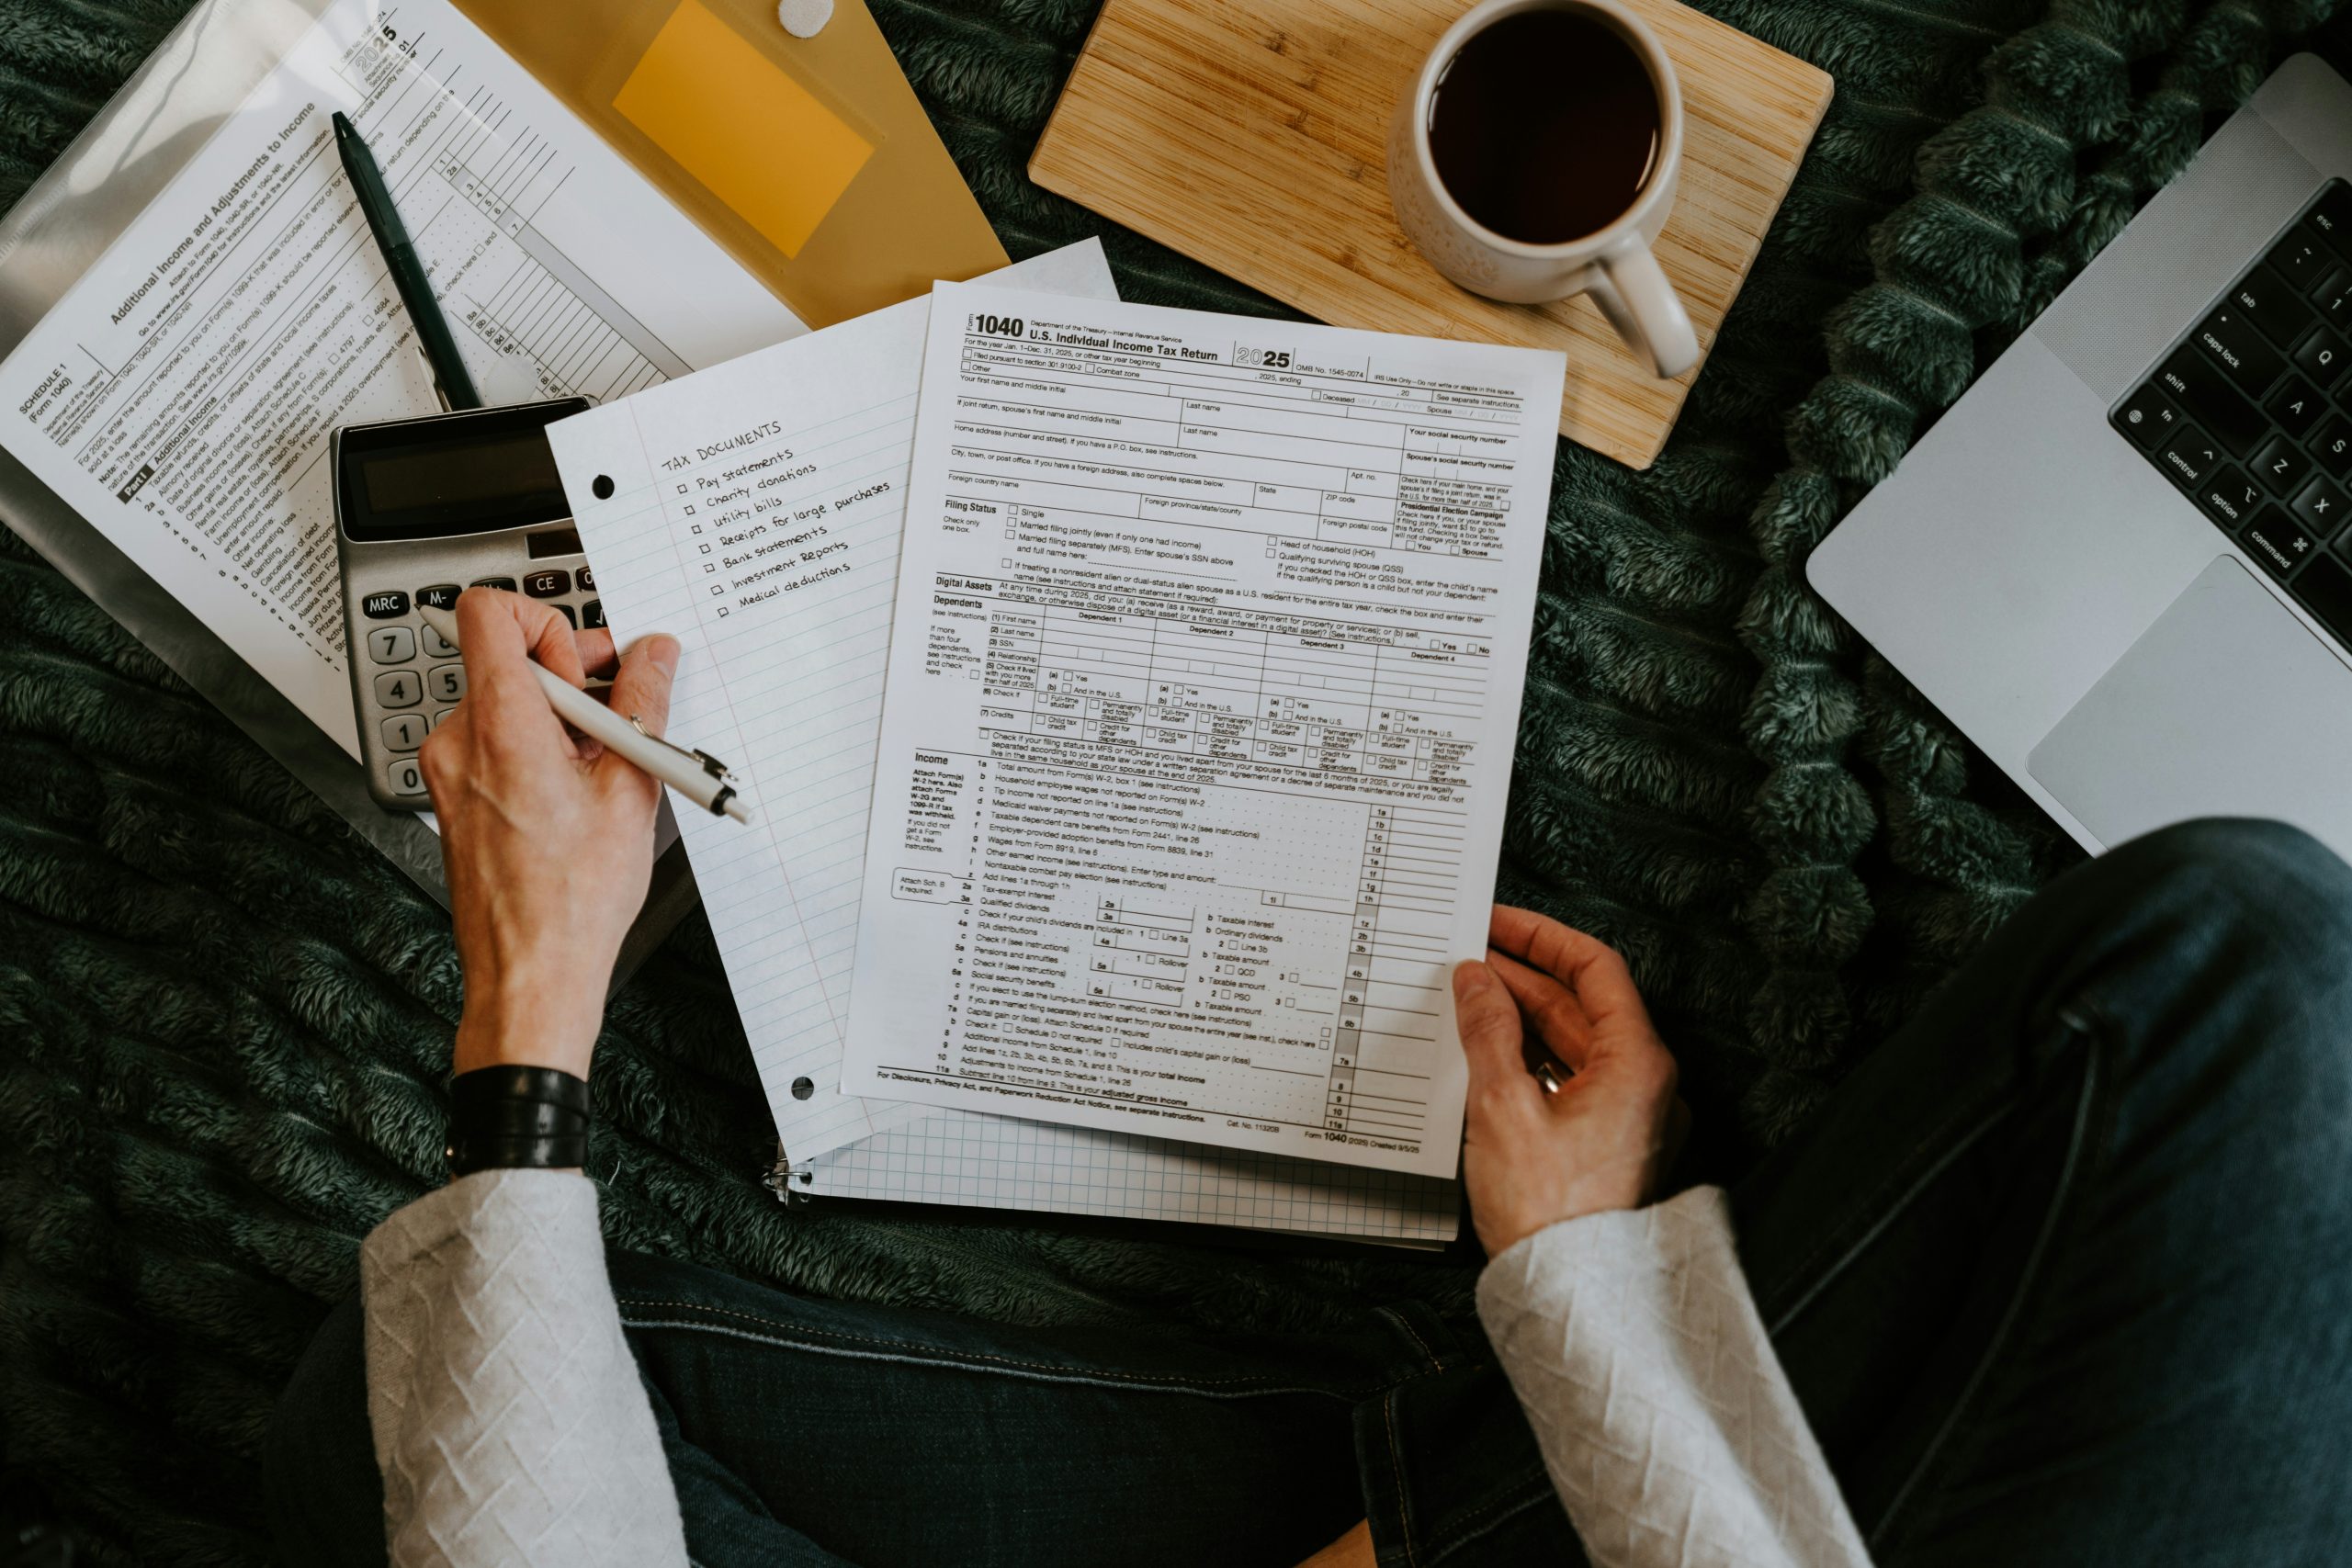
Talk Openly About Money
Money conversations can be uncomfortable, but avoiding them often creates more pressure. Couples and older children can benefit from honest, age-appropriate discussions about priorities and limits. This might include explaining why a holiday needs saving for, why certain subscriptions are being cancelled or why packed lunches are replacing café trips.
Children also learn good habits by watching adults make thoughtful decisions. Giving them pocket money, encouraging saving and helping them compare prices can build confidence and responsibility.
Prepare for Unexpected Costs
Every family faces surprise expenses at some point. A broken boiler, damaged phone, school payment or urgent car repair can quickly disrupt the month. Even a small emergency fund can make these moments easier to manage.
Setting aside a fixed amount each payday, however modest, creates a financial cushion. Keeping this money separate from everyday spending reduces the temptation to dip into it. Over time, the fund can provide reassurance and prevent reliance on expensive borrowing.
Review Regular Bills
Many households pay for services they no longer use or could get cheaper elsewhere. Broadband, mobile phone contracts, insurance, TV packages and energy tariffs are worth reviewing regularly. Renewal dates matter, as prices can rise when introductory offers end.
It is also worth checking bank statements for forgotten subscriptions. Streaming services, apps, memberships and free trials that became paid plans can quietly add up. Cancelling just a few unused payments may free up money for savings or family treats.
Make Saving Feel Achievable
Saving does not always require large amounts. Small, consistent contributions can still make a meaningful difference. Families might set up separate pots for holidays, Christmas, school costs or home improvements. Naming each pot gives the money a purpose and makes progress easier to see.
Automatic transfers can also help. Moving money into savings on payday means it is less likely to be spent accidentally. If income varies, saving a percentage rather than a fixed amount may feel more manageable.
Choose Value, Not Just the Lowest Price
The cheapest option is not always the best value. Buying poor-quality shoes, appliances or school items may lead to replacing them sooner. On the other hand, expensive does not always mean better. The aim is to balance price, durability and usefulness.
Families can benefit from reading reviews, buying second-hand where sensible and waiting for sales on planned purchases. Taking time before buying also helps avoid impulse spending.
Keep Decisions Simple
Financial wellbeing is not about making perfect choices every day. It is about creating simple routines that reduce pressure and support family life. A clear budget, planned meals, regular bill checks and honest conversations can all make daily decisions easier.
When families understand their priorities and prepare for common costs, money becomes less of a constant worry. Small steps, repeated often, can create more stability, more choice and a calmer home.